SpaceX is no longer merely a satellite-internet disruptor. It is moving deeper into the U.S. wireless battlefield—and Verizon is paying the market’s most visible price. Verizon shares were headed for their worst day since 2002 after SpaceX announced a spectrum deal with Grain Management, a development that immediately sharpened concerns about competition across the American telecom industry.
The significance goes beyond one ugly session for $VZ. Through Starlink, SpaceX is pursuing a broader U.S. network strategy that could challenge the assumptions supporting incumbent carriers, their valuations and the income case built around telecom dividends.
A spectrum deal with strategic weight
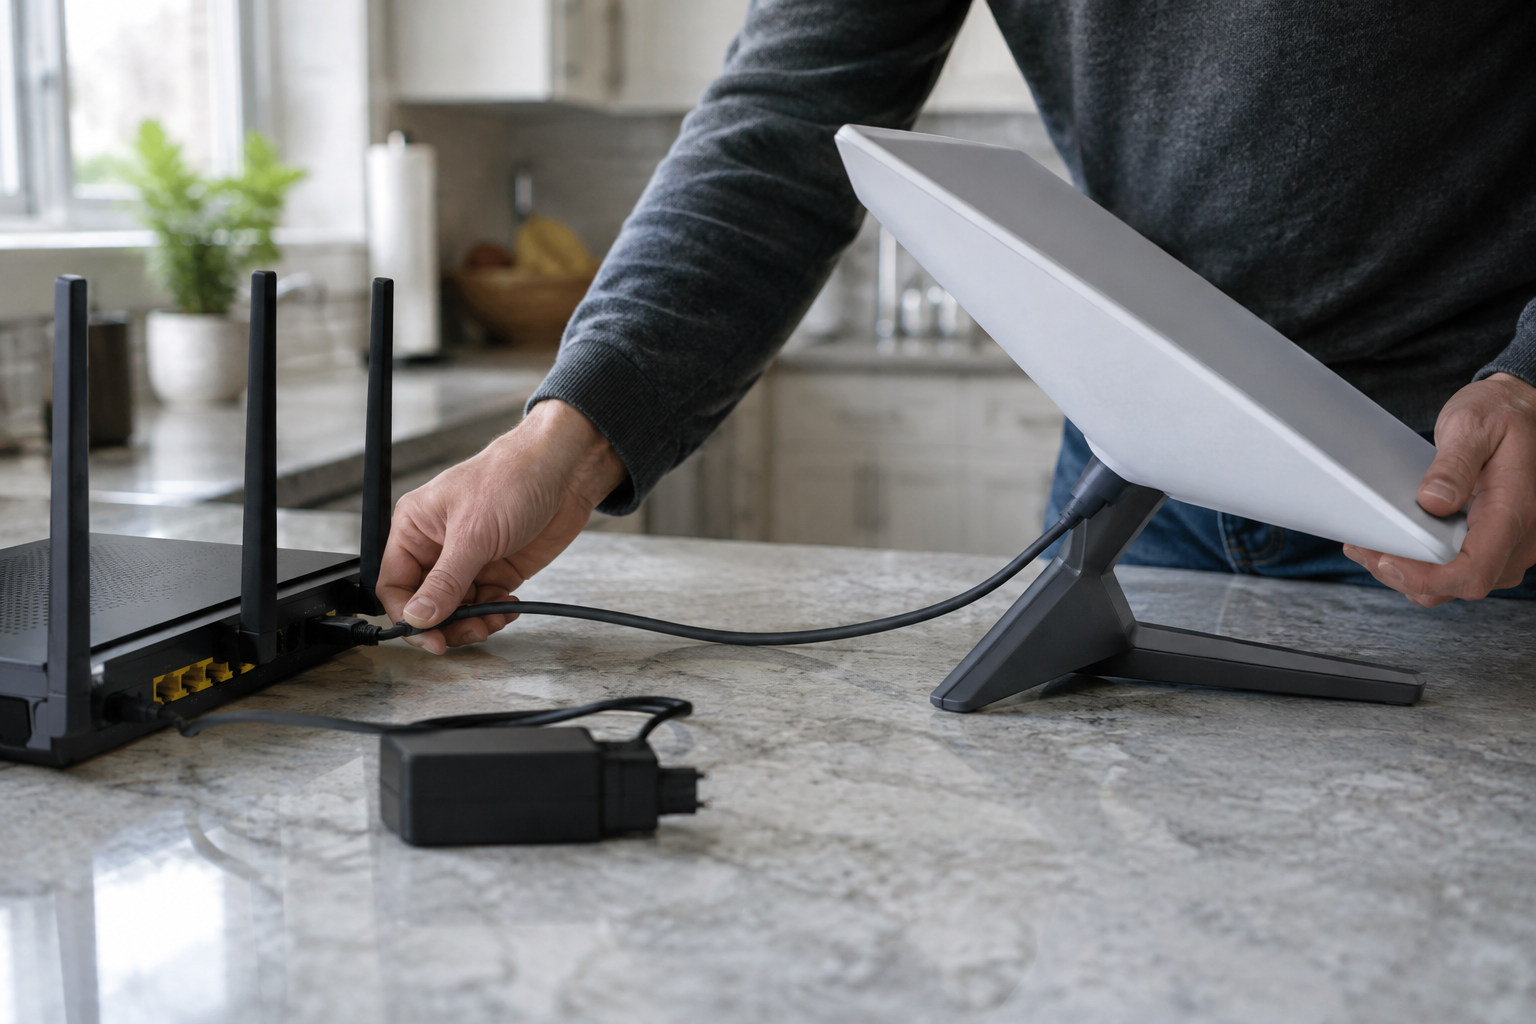
SpaceX’s agreement with Grain Management is intended to expand its U.S. network ambitions through Starlink. That matters because spectrum is the essential operating resource behind wireless connectivity. Access to additional spectrum may give SpaceX more flexibility as it develops a deeper presence in the U.S. telecom market.
The market is therefore treating the announcement as more than a technology headline. It signals that SpaceX may be assembling a stronger competitive platform against established carriers with long-standing wireless operations. The question for investors is no longer whether satellite connectivity can complement traditional networks. It is whether SpaceX could increasingly compete with them.
That distinction is crucial. A complementary service can broaden the market for connectivity. A more direct wireless competitor could pressure customer relationships, pricing power and the valuation framework applied to legacy carriers. The market reaction in Verizon, AT&T and T-Mobile indicates that traders are taking the second possibility seriously.
Why Verizon absorbed the immediate shock
Verizon’s move toward its worst day since 2002 reflects the market’s sensitivity to any threat that could weaken the company’s competitive position. The reaction does not establish that SpaceX will quickly displace incumbent wireless providers. It does show that investors are reassessing the durability of the existing industry structure.
Verizon, AT&T and T-Mobile have built their businesses around established wireless networks and recurring customer relationships. SpaceX’s Starlink ambitions introduce a different model—one tied to satellite connectivity and an expanding network footprint. If that model reaches further into mainstream U.S. telecom, the traditional carriers may face another source of competitive pressure at a time when investors already scrutinize their growth prospects.
For Verizon shareholders, the issue is especially important because the stock is also held for income. When a telecom company is valued partly for its dividend, a new competitive threat can affect more than expected revenue growth. It may influence how investors view the sustainability, flexibility and strategic importance of that payout over time.
The read-through for AT&T and T-Mobile
AT&T and T-Mobile are not spectators in this development. SpaceX’s expansion through Starlink could raise the competitive temperature for all three major legacy carriers. The precise commercial impact remains uncertain, but the spectrum deal suggests that SpaceX intends to build capabilities rather than remain confined to a narrow satellite niche.
That creates a valuation question for the group. Investors may place a greater premium on execution, network differentiation and the ability to retain customers if a new entrant gains scale. The market does not need to assume immediate disruption to impose pressure on telecom multiples; it only needs to believe that future competition could be more intense than previously expected.
Telecom tower REITs provide the contrarian angle
Here is the part of the reaction that deserves more attention: telecom tower REIT stocks jumped following the SpaceX-Grain Management spectrum deal. The contrast is revealing. The same announcement that threatens to unsettle incumbent carrier valuations may be interpreted as supportive for the infrastructure businesses that enable wireless connectivity.
That response suggests investors may see network expansion as a potential tailwind for tower infrastructure, even as they question the position of individual carriers. If wireless competition expands demand for network capacity and coverage, telecom tower REITs could occupy a more attractive position in the market’s evolving infrastructure map. The move does not eliminate sector risks, but it highlights a secondary investment narrative distinct from the pressure on Verizon, AT&T and T-Mobile.
The bottom line is straightforward: SpaceX’s deal with Grain Management raises the stakes in U.S. telecom. Verizon’s worst-day setup since 2002 shows how quickly markets can reprice incumbents when a credible new competitive threat emerges. Meanwhile, the jump in telecom tower REIT stocks suggests that the winners from network disruption may not be the carriers themselves, but the owners of the infrastructure required to support the next phase of connectivity.
Bull/Bear Verdict
Bull Case: The spectrum deal may expand Starlink’s U.S. network ambitions and support telecom infrastructure demand, as indicated by the jump in telecom tower REIT stocks after the announcement.
Bear Case: SpaceX’s deeper move into telecom could intensify competitive pressure on Verizon, AT&T and T-Mobile, with Verizon’s worst-day setup since 2002 underscoring the potential valuation impact.