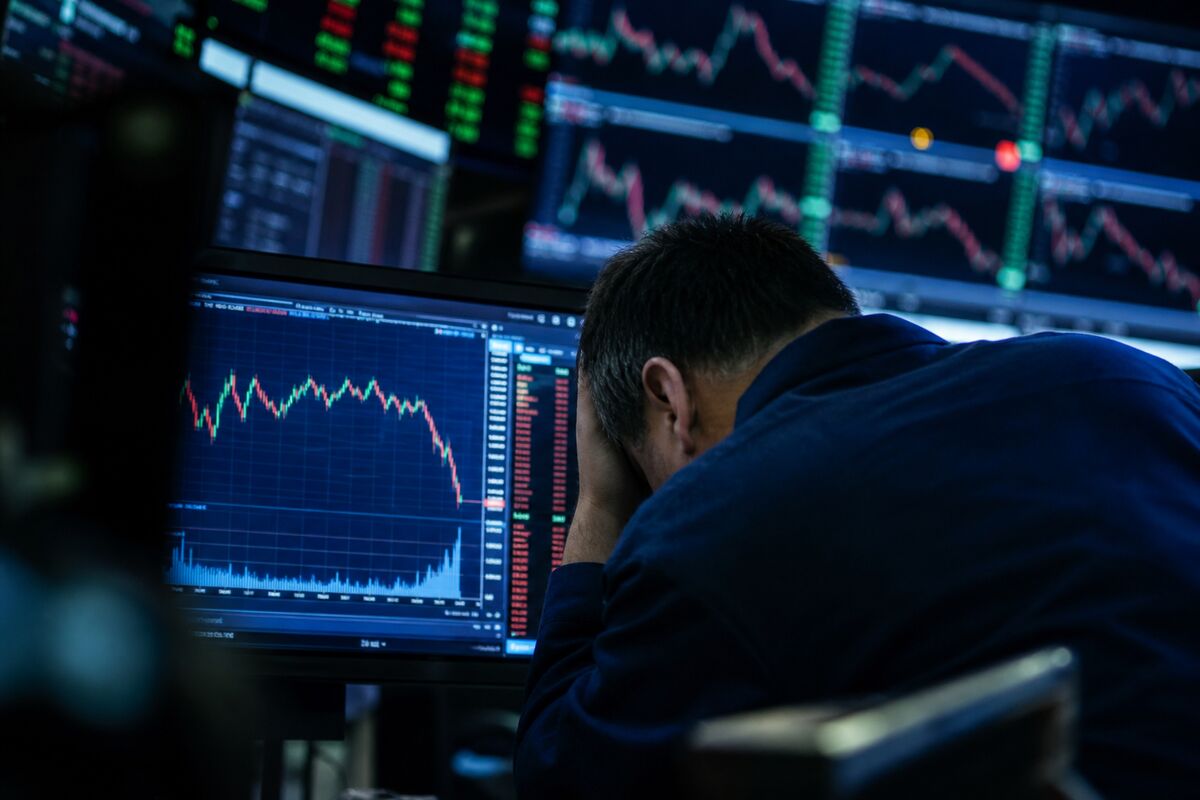
Wall Street’s fear gauge is flashing a warning, not offering reassurance. The CBOE Volatility Index, or VIX, moved more than 11 points intraday Thursday—its biggest one-day swing since April 9—as the broader US equity selloff turned into what CNBC described as “Thursday’s terrible market.”
More striking than the size of the move was the reaction from traders: even after that sharp jump, some argued the VIX should be higher given current market conditions. That is a blunt signal that institutional investors may still view the market’s visible level of fear as insufficient compensation for the risks they are managing.
The VIX is designed to reflect expected volatility in the US equity market through options pricing. When it rises rapidly, the message is not simply that stocks are moving. It suggests options traders are demanding more protection against larger swings, while portfolio managers may be reassessing how much downside exposure they are willing to carry.
Why the intraday move matters
A move of more than 11 points in a single session is significant because it compresses a large amount of repricing into a short period. The VIX’s previous comparable one-day swing occurred on April 9, giving Thursday’s action a clear historical reference point without requiring investors to rely on an unreported closing level or percentage change.
That comparison matters for positioning. A steadily rising volatility gauge can indicate mounting concern. A sharply rising gauge, by contrast, can signal that investors are scrambling to adjust exposures as market conditions deteriorate. The distinction is important: orderly caution and urgent hedging are not the same thing.
The latest move came during a broader US equity selloff, linking the volatility spike directly to pressure in the stock market. When equities fall and implied volatility rises at the same time, the result can be a more difficult environment for portfolios that rely on stable prices, consistent liquidity or limited daily moves.
Options desks become the pressure point
For options markets, a rapidly rising VIX can reflect stronger demand for puts and other forms of downside protection. It may also raise the cost of hedging, making portfolio insurance more expensive precisely when investors are most eager to obtain it. That dynamic can complicate decisions for institutions attempting to reduce risk after a selloff has already begun.
It can also affect positioning across the market. Traders who had previously sold volatility or maintained exposure to calm conditions may face pressure to reduce those positions. Meanwhile, investors seeking protection may find that the market is repricing risk faster than they can adjust. The result could be additional trading activity as participants rebalance hedges, alter option structures or reduce equity exposure.
“The fear gauge should be even higher” is more than a dramatic trading-floor comment. It suggests that some market participants believe current options pricing still does not fully reflect the uncertainty embedded in Thursday’s selloff.
A warning, not a standalone forecast
The VIX does not predict the next market move by itself. A higher reading can accompany continued stress, but it can also reflect a rapid rush for protection that later stabilizes. The more useful conclusion is narrower: Thursday’s more-than-11-point intraday move shows that institutional risk appetite and hedging demand were being repriced quickly.
That repricing deserves attention because it can influence both equity portfolios and options activity even after the initial selloff fades. Traders’ insistence that the VIX may still be too low indicates that the market’s risk assessment remains unsettled. Until that disagreement is resolved, volatility itself may remain a central force in US equity trading.
CNBC’s report on Thursday’s VIX move underscores the central point: the largest one-day swing since April 9 arrived alongside a severe equity selloff, yet some traders still viewed the fear gauge as understated.
Bull/Bear Verdict
Bull Case: The VIX’s more-than-11-point intraday jump may indicate that hedging demand is already being aggressively repriced, potentially allowing volatility to stabilize if the broader selloff loses momentum.
Bear Case: Traders’ view that the VIX should be even higher, combined with its biggest one-day swing since April 9, suggests institutional risk appetite may remain under pressure and that further market stress could still be reflected in options pricing.