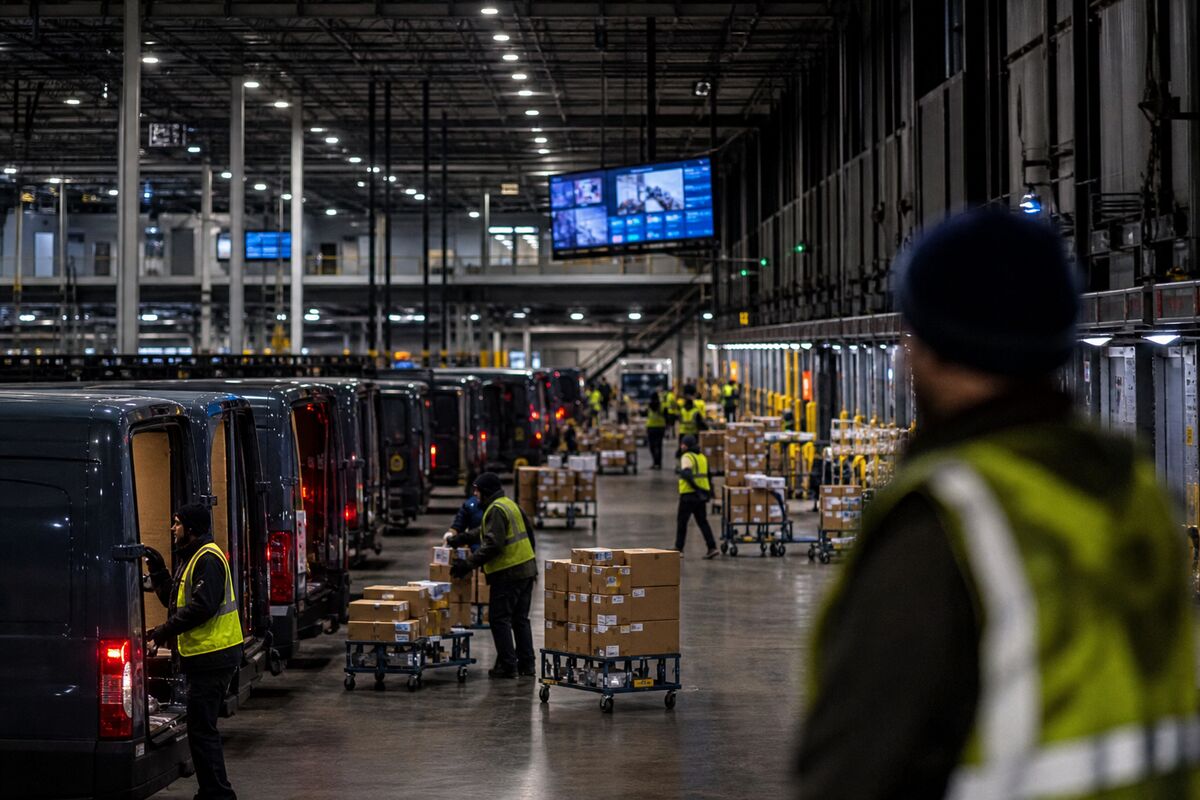
UPS is betting that the next leg of logistics growth may come from what travels inside the package—not simply how many packages move. The company announced an agreement to acquire Smartways Logistics, a healthcare logistics services provider operating in Australia and New Zealand. For investors watching $UPS, the transaction represents a push into a more specialized segment at a time when traditional package volumes, margins and long-term growth remain central market concerns.
The deal does not come with a disclosed purchase price, closing terms or projected financial impact in the information provided. That limits what investors can responsibly conclude today. But the strategic direction is clear: UPS is seeking to broaden its healthcare supply-chain capabilities and extend that offering into the Asia-Pacific region. The move may matter less as an immediate earnings event than as another indicator of how large logistics companies are pursuing more complex, higher-value services.
UPS’s agreement with Smartways adds healthcare logistics exposure in Australia and New Zealand, giving the US-listed company an opportunity to expand its presence in a sector where reliability, handling requirements and supply-chain coordination can matter as much as speed. Those characteristics may create a more specialized service mix than conventional parcel delivery.
That distinction is important. Traditional parcel networks are highly sensitive to shipment volumes, pricing, labor costs and broader economic activity. Healthcare logistics, by contrast, may offer a different demand profile and a greater emphasis on operational precision. The acquisition could therefore support UPS’s effort to diversify its growth beyond standard parcel delivery, although the source does not provide enough information to determine the deal’s eventual contribution to revenue, margins or earnings.
Why the Asia-Pacific angle matters
For North American investors, the geographic expansion is part of the investment case. UPS is not merely adding another domestic logistics operation; it is adding healthcare supply-chain capabilities in Australia and New Zealand. That may give the company a broader platform from which to serve healthcare-related customers across the Asia-Pacific region.
Still, geographic expansion should not be confused with guaranteed growth. The announcement establishes the acquisition agreement, but it does not disclose integration plans, financial targets or expected synergies. Investors may ultimately focus on whether UPS can incorporate Smartways into its broader healthcare logistics strategy without adding disproportionate complexity or cost.
A signal in a demanding logistics market
The transaction also fits the broader pattern of M&A activity in logistics. Companies in the sector are looking for ways to strengthen networks, add capabilities and diversify their exposure as investors remain attentive to soft package volumes, margin pressure and the need for credible growth avenues.
Healthcare logistics may be attractive precisely because it is more specialized. A service offering built around healthcare supply chains could potentially deepen customer relationships and reduce reliance on undifferentiated parcel volume. Yet that potential must be tested against execution. The source provides no purchase-price details or financial outlook, so the market cannot yet measure whether the agreement is meaningfully accretive or how quickly it might affect UPS’s results.
The disciplined interpretation is straightforward: UPS is expanding its healthcare logistics reach through Smartways, and that may strengthen its long-term diversification strategy. The near-term investment thesis remains incomplete until the company provides more detail on the transaction and its expected financial consequences. The announcement is strategic evidence—not an earnings forecast. Investors can review the company announcement for the sourced details.
Bull/Bear Verdict
Bull Case: The Smartways agreement may give $UPS broader healthcare supply-chain capabilities in Australia and New Zealand, potentially creating a more specialized growth avenue beyond traditional parcel volumes.
Bear Case: With no purchase price, closing terms or projected financial impact provided, investors cannot yet determine whether the deal will offset concerns about soft package volumes, margins or execution complexity.