Strathcona Resources’ proposed acquisition of Greenfire Resources, valued at up to C$2.9 billion, is more than a large Canadian energy transaction. It is another clear signal that ownership of oil sands production is becoming increasingly concentrated among operators with the scale to manage heavy-oil assets.
The cash-and-stock deal puts Canadian energy-sector M&A back in focus while giving investors a direct case study in how producers may pursue growth when strategic control of heavy-oil resources matters as much as near-term production. The headline figure is substantial, but the structure also makes the transaction relevant to both companies’ shareholders.
A sizeable step in oil sands consolidation
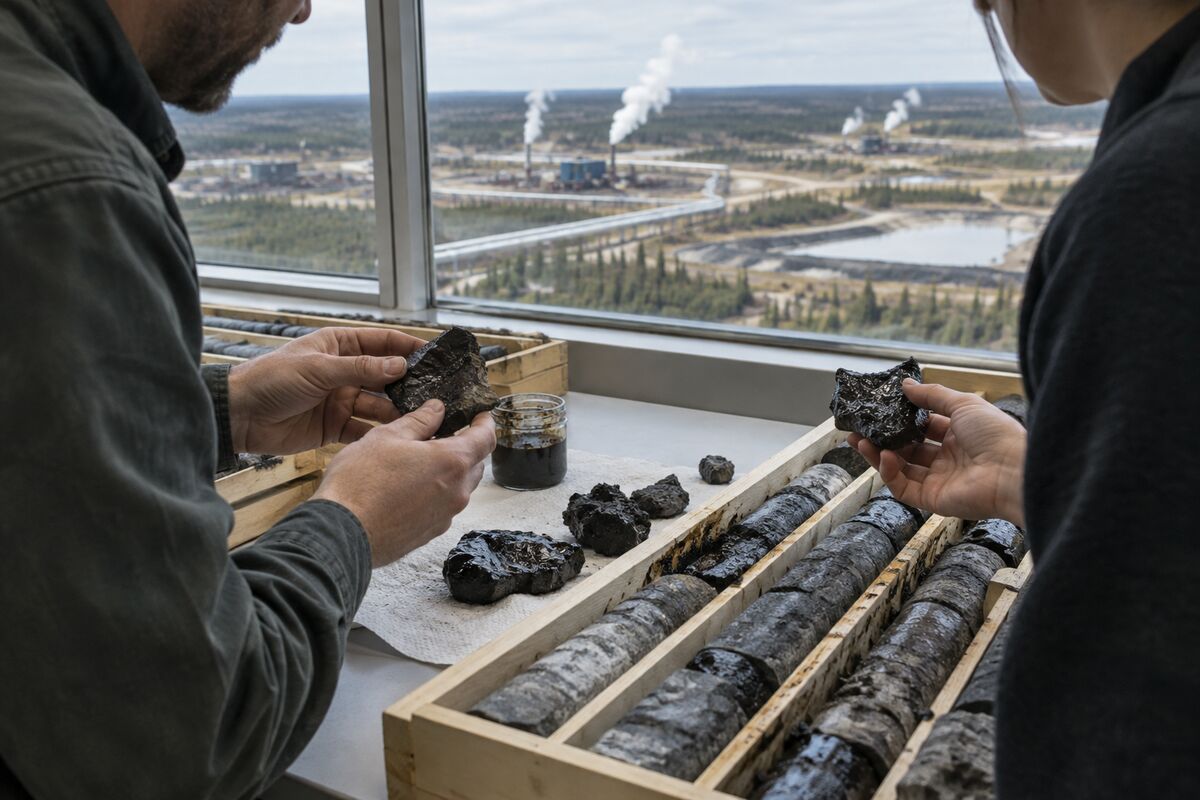
Strathcona has agreed to acquire Greenfire in a transaction valued at up to C$2.9 billion. The deal combines cash and stock consideration, creating a larger corporate platform while extending the consolidation trend across Canada’s oil sands industry.
That matters because heavy-oil production is not simply interchangeable with every other form of crude. Oil sands assets represent long-life resource positions with distinct operating requirements and market considerations. Combining ownership under a larger producer could provide strategic control over a broader heavy-oil portfolio, although the assignment does not provide operational forecasts or projected financial benefits.
For the Canadian market, the transaction reinforces a straightforward theme: scale remains a central feature of energy-sector strategy. A deal of up to C$2.9 billion is large enough to reshape the ownership profile of the assets involved and could encourage investors to examine which other Canadian producers might become consolidation candidates.
Why the cash-and-stock structure matters
Cash-and-stock consideration gives the transaction two visible dimensions for shareholders. The cash component offers direct consideration, while the stock component links part of the deal’s value to ownership in the combined business. The source does not provide the allocation between cash and shares, so the headline valuation remains the key disclosed figure.
That structure also means investors may assess the transaction differently depending on their focus. Greenfire shareholders may evaluate the stated value of up to C$2.9 billion and the balance between immediate and continuing exposure. Strathcona shareholders, meanwhile, may focus on how the acquisition changes the company’s scale and strategic position in heavy oil.
Heavy oil and changing crude dynamics
The deal arrives as crude-price dynamics continue to shape the strategic value of different production types. No specific crude price or forecast is provided with the transaction, but the acquisition highlights why heavy-oil resources remain important to Canadian energy investors. Producers are not evaluating assets solely through a single price snapshot; they are also weighing resource depth, operating scale and long-term ownership.
Investors tracking Canadian energy M&A should therefore treat the C$2.9 billion maximum valuation as both a transaction metric and a consolidation marker. It indicates that control of heavy-oil assets can command significant strategic attention, while the cash-and-stock format shows that large deals can distribute consideration across immediate cash and equity ownership.
For now, the central fact is clear: Strathcona’s proposed Greenfire acquisition would deepen concentration in Canadian oil sands ownership. Its final importance will depend on execution and the value ultimately realized, but the announced up-to-C$2.9 billion price tag makes this a consequential transaction for the Canadian energy landscape. Seeking Alpha reported the proposed cash-and-stock transaction.
Bull/Bear Verdict
Bull Case: The proposed up-to-C$2.9 billion acquisition could strengthen Strathcona’s strategic position in heavy oil and reinforce the value of scale in Canadian oil sands ownership.
Bear Case: The deal’s maximum C$2.9 billion value and cash-and-stock structure leave shareholders exposed to execution and valuation uncertainty, while the source provides no further financial terms or operating forecasts.