Strathcona Resources’ agreement to acquire Greenfire Resources for a cash-and-stock consideration valued at C$2.7 billion to C$2.9 billion, including debt, puts a hard number on one of the Canadian energy sector’s larger recent consolidation transactions. It also places long-life oilsands and heavy-oil assets back at the center of the market’s valuation debate.
For Canadian energy investors and merger-arbitrage watchers, the transaction matters for two reasons: it expands Strathcona’s heavy-oil footprint while giving Greenfire shareholders a deal with both cash and equity components. The headline valuation is substantial, but the structure means the economics require closer attention than a simple all-cash acquisition.
A sizeable consolidation move
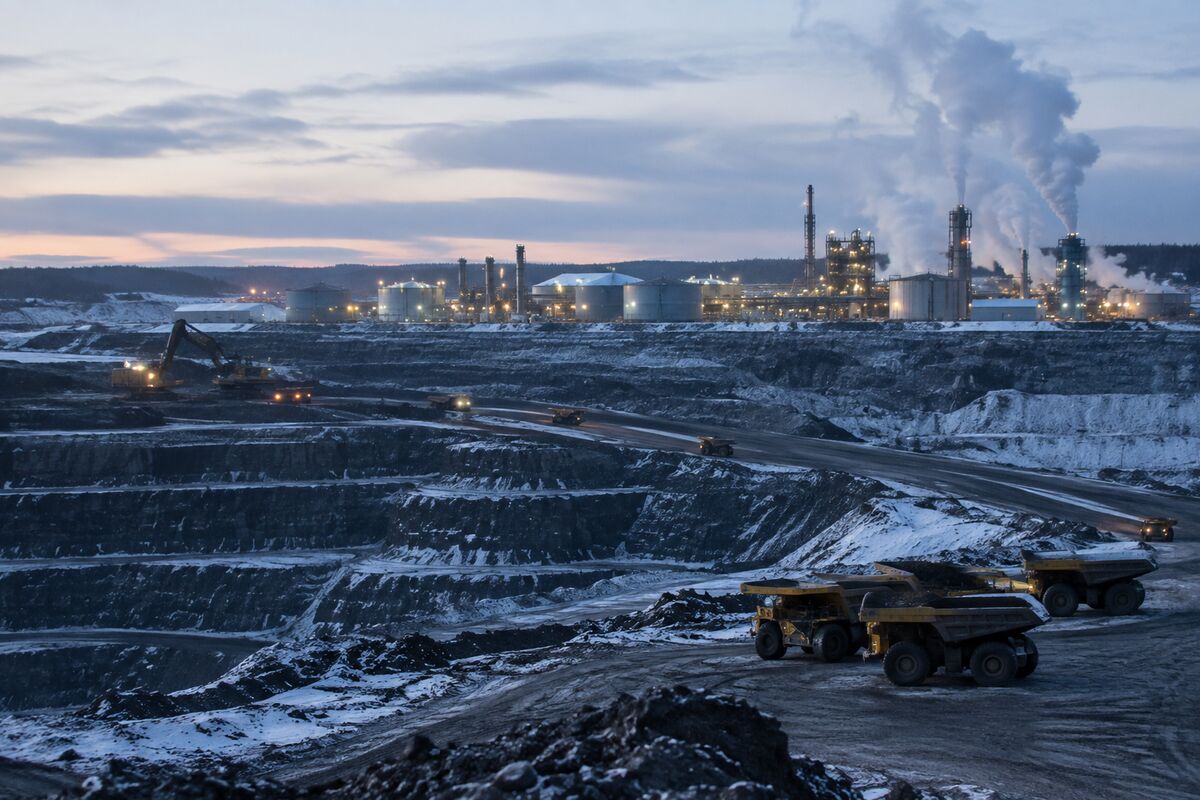
Strathcona and Greenfire are both Canadian companies focused on long-life oilsands and heavy-oil assets. By combining the businesses, Strathcona is pursuing greater scale in a part of the energy industry defined by large, long-duration resource bases rather than short-cycle production alone.
The C$2.7 billion to C$2.9 billion valuation, including debt, makes the transaction one of the larger recent consolidation deals in Canada’s energy sector. That scale is important. It indicates that heavy-oil assets remain significant enough to support a multibillion-dollar corporate transaction, even as investors continue to assess the capital intensity and operating characteristics associated with oilsands production.
The strategic logic is relatively direct: Strathcona is expanding its existing heavy-oil exposure, while Greenfire becomes part of a broader Canadian producer. The available deal information does not provide additional operating targets or financial forecasts, so the most defensible conclusion is narrower: the transaction is a deliberate expansion of Strathcona’s position in long-life oilsands and heavy-oil resources.
What the valuation may say about heavy oil
A valuation range of C$2.7 billion to C$2.9 billion, including debt, offers a fresh reference point for how the industry may view heavy-oil assets. It does not, by itself, establish a broader sector multiple or provide a direct benchmark for every oilsands producer. Still, the size of the consideration suggests that long-life heavy-oil resources continue to command attention in corporate strategy.
For investors, the signal is less about a single implied ratio and more about transaction willingness. Strathcona is committing to a major combination in a segment where asset duration and resource scale are central to the investment case. That may indicate confidence in the strategic value of Greenfire’s assets, although the deal terms alone do not determine how the combined business will perform.
Why the cash-and-stock structure matters
The transaction’s cash-and-stock structure gives the announcement two distinct market dimensions. Greenfire shareholders are not simply evaluating a fixed cash exit; they are also receiving exposure to the acquiring company through the equity component. As a result, the final value can be viewed through both the stated transaction range and the value of the shares included in the consideration.
That distinction is particularly relevant for merger-arbitrage watchers. The key questions are whether the transaction advances as agreed, how the cash-and-stock mix translates into shareholder value, and how the combined company’s equity is valued by the market. The assignment does not provide a share-exchange ratio, closing date or other transaction conditions, so those terms should not be inferred from the headline valuation.
Greenfire shares attracted significant attention following the announcement, underscoring the market’s focus on the transaction. For TSX-listed energy investors, the broader takeaway is that Canadian oilsands consolidation remains active enough to produce a deal of this scale—and that heavy-oil valuations are once again being tested through corporate action.
The BOE Report’s coverage identifies the transaction as a deal valued at up to C$2.9 billion, including debt. That figure is the central data point for assessing the market significance of Strathcona’s expansion.
Bull/Bear Verdict
Bull Case: The C$2.7 billion–C$2.9 billion, including-debt valuation may suggest that long-life oilsands and heavy-oil assets retain strategic value, while Strathcona’s expansion could reinforce a fresh wave of Canadian consolidation.
Bear Case: The cash-and-stock structure and the absence of disclosed exchange terms leave uncertainty around the final shareholder value, while the headline valuation alone does not establish broader heavy-oil multiples or operating returns.