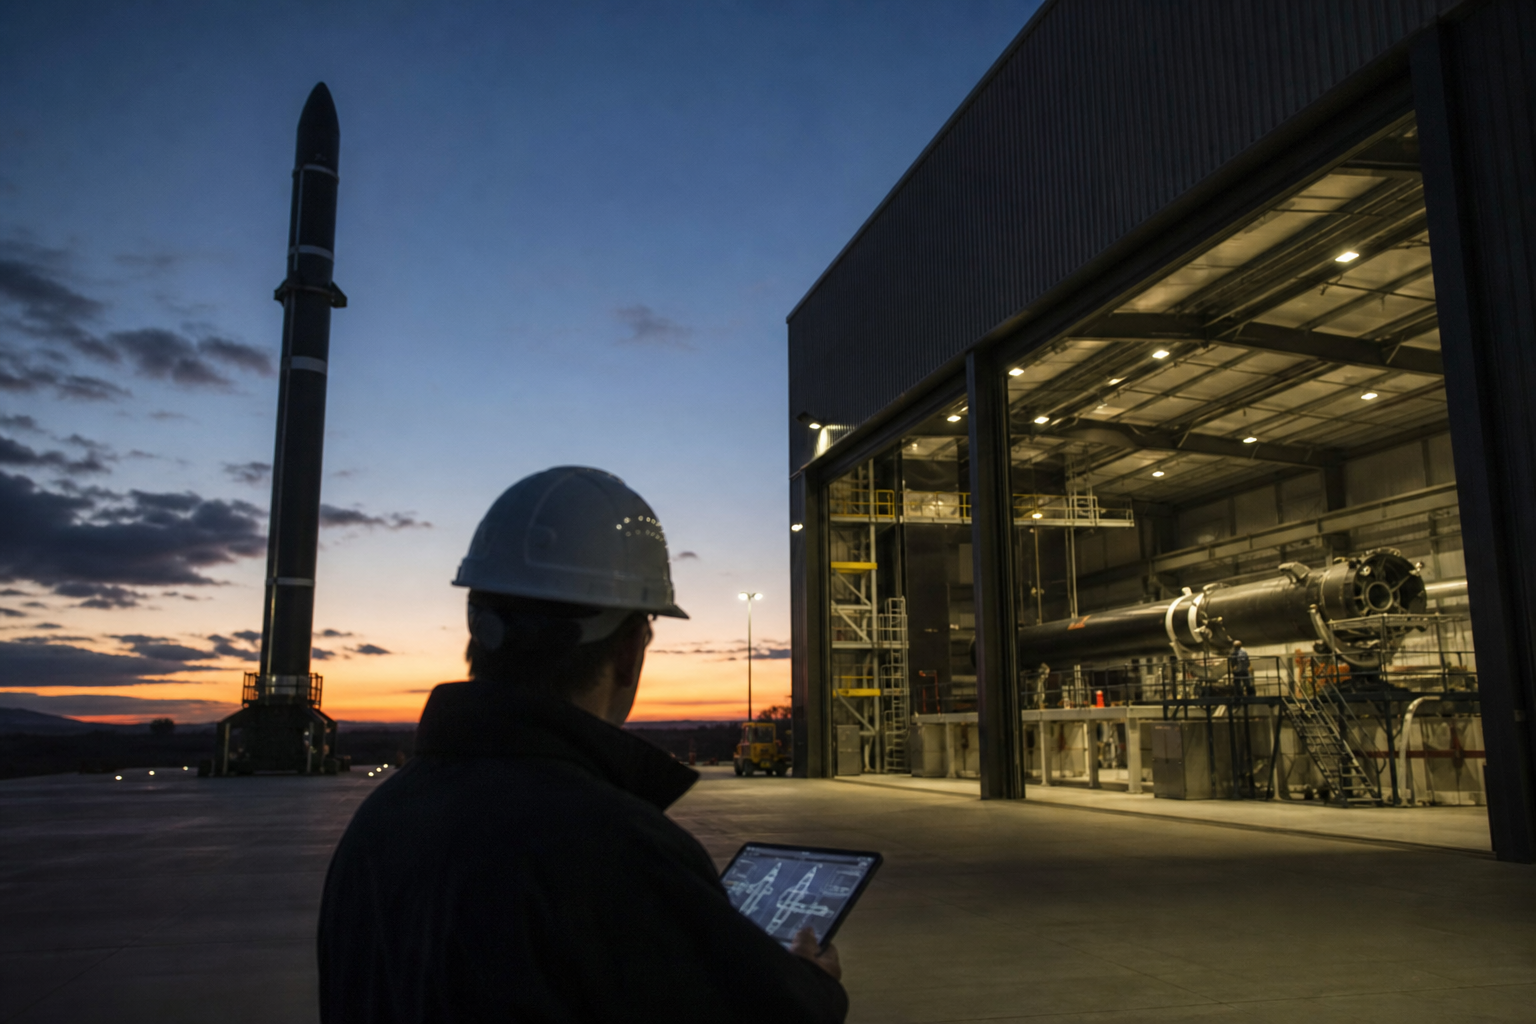
When it comes to the high-stakes world of space technology, few companies have made waves quite like Rocket Lab Corporation ($RKLB). Now, with the recent completion of a $1.94 billion at-the-market (ATM) equity offering, Rocket Lab is poised to embark on a transformative journey through its acquisition of Iridium. But as any seasoned investor knows, even the most promising ventures come with their own set of risks and rewards.
The $1.94 billion raised through the ATM offering marks a significant milestone for Rocket Lab, enabling the company to fully fund its pending acquisition of Iridium, a key player in satellite communications. This strategic move could bolster Rocket Lab's business model by introducing recurring revenue streams, a critical factor for long-term sustainability in the often volatile aerospace sector.
The Implications of the Iridium Acquisition
The acquisition of Iridium represents a pivotal shift for Rocket Lab. By integrating Iridium’s established satellite constellation and communication services, Rocket Lab could enhance its operational capabilities and broaden its market reach. This synergy could allow Rocket Lab to diversify its revenue streams and tap into the lucrative satellite communications market, which has been gaining traction in recent years.
Moreover, the potential for recurring revenue through subscription services and data offerings could provide a more stable financial footing for Rocket Lab. Investors may appreciate the shift from a traditional project-based revenue model to a more predictable income structure, aligning with the broader trends in the tech and defense industries.
Risks and Opportunities
However, the road ahead is not without its challenges. The completion of the ATM offering inevitably introduces dilution concerns for existing shareholders. Investors must consider how this dilution could impact their ownership stakes and the overall market perception of Rocket Lab's stock performance. While the infusion of capital is necessary for funding the acquisition, it could also lead to short-term volatility as the market digests the implications of increased shares outstanding.
Additionally, the integration of Iridium into Rocket Lab's operations may not be seamless. Investors should remain cautious about the potential operational hurdles that could arise during the merging of two distinct corporate cultures and business strategies. Successful integration will be crucial to realizing the anticipated synergies and maximizing the acquisition's value.
On the flip side, the acquisition could position Rocket Lab as a leader in the burgeoning satellite communications market, particularly as demand for global connectivity continues to surge. With the right execution, Rocket Lab could capitalize on this trend, unlocking substantial growth opportunities that may outweigh the risks.
Conclusion
As Rocket Lab moves forward with its acquisition of Iridium, the stakes are undeniably high. The successful completion of the $1.94 billion ATM offering provides a solid foundation for this ambitious venture, but investors must remain vigilant in assessing both the opportunities and risks that lie ahead. The aerospace sector is notorious for its unpredictability, and while the potential for recurring revenue is enticing, it is critical to approach this investment with a balanced perspective.
For those looking to navigate this evolving landscape, staying informed and prepared for market fluctuations will be essential as Rocket Lab embarks on this new chapter in its corporate journey.
Source