Inflation has re-entered the trading conversation with force. A hotter-than-expected September CPI report sent stocks lower, pushed Treasury yields higher and strengthened the US dollar as markets reassessed how quickly the Federal Reserve can ease policy.
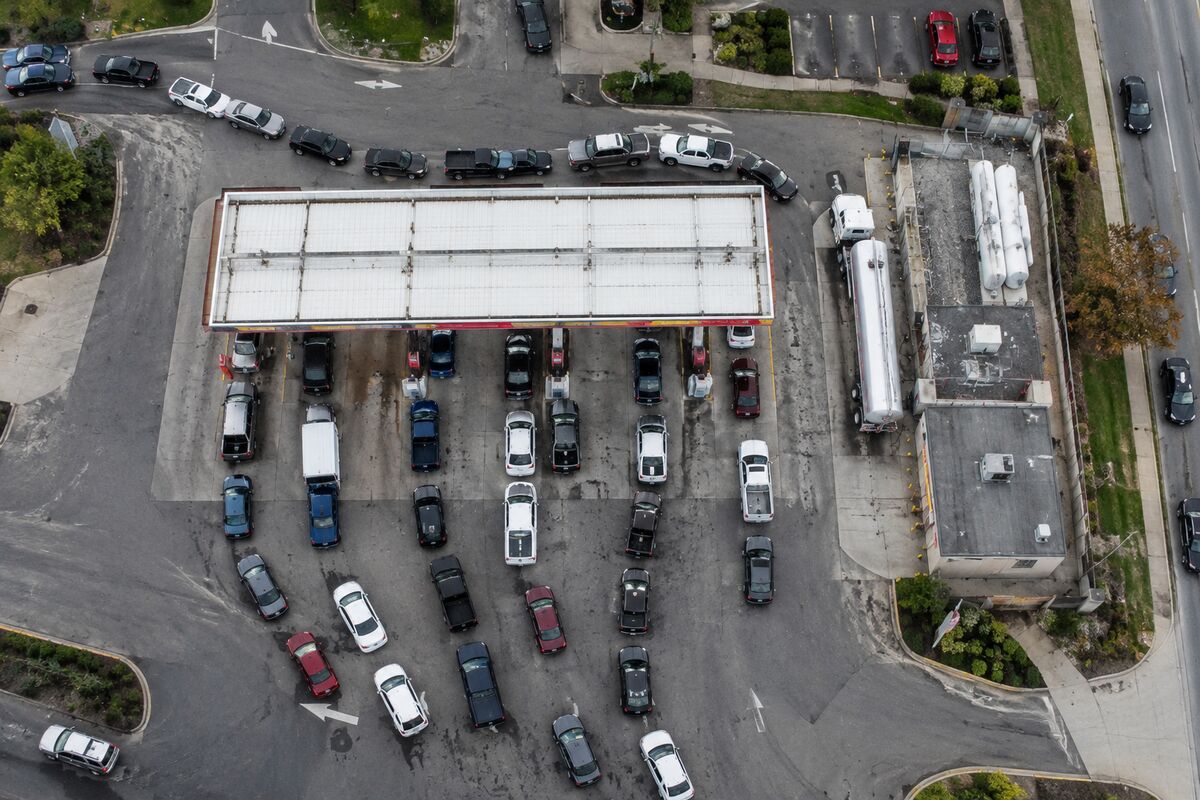
The immediate culprit was energy. Gasoline prices rose 9.1% in September after increasing 3.9% in August, while fuel oil prices climbed 15.3%. That combination gives traders a clear inflation problem to price: the headline pressure was not merely theoretical, and core CPI was also firmer than expected.
Reuters reported that US consumer prices accelerated in September, with the core measure exceeding expectations as well. The details matter because the Federal Reserve’s rate path depends not only on whether inflation is moving lower, but also on whether that progress is broad enough and durable enough to justify further cuts.
Energy prices can be volatile, but the market’s first response was decisive. Stocks moved lower as investors confronted the possibility that restrictive monetary policy may remain in place for longer. Treasury yields moved higher, reflecting a reduction in confidence around the timing or pace of future Federal Reserve rate cuts. The US dollar strengthened as the interest-rate differential narrative shifted in its favor.
That is the central trading message from this report: the market is no longer looking at a clean, one-way disinflation story. Gasoline’s 9.1% increase, following a 3.9% rise in August, represents a sharp acceleration in a highly visible consumer cost. Fuel oil’s 15.3% increase reinforces the same point. Even if energy does not determine the long-term inflation trend by itself, it can influence expectations and complicate the policy debate.
Why the rate path matters
The report does not automatically eliminate the prospect of future rate cuts. It does, however, make the timing and pace of those cuts more difficult for markets to price with confidence. A firmer core CPI reading leaves less room for policymakers to treat the inflation fight as finished, while the jump in energy costs raises the risk that progress toward the Federal Reserve’s objective could become uneven.
For Treasury traders, the reaction is straightforward: higher yields indicate that investors are demanding more compensation for the possibility of rates staying elevated. For equity traders, the pressure comes through valuation and liquidity expectations. When yields rise, the market must reassess the appeal of stocks against a less supportive interest-rate backdrop. The initial move lower in stocks reflects that adjustment, not necessarily a final verdict on the economy.
The US dollar’s strength fits the same framework. As the CPI report reduced expectations for rapid policy easing, the dollar benefited from the prospect of a relatively firmer US rate outlook. Technical analysis from ForexLive tracks the dollar’s market reaction and the key levels traders are watching after the inflation release.
The historical lesson is familiar: markets often react first to the direction of inflation, then to its composition. September delivered both a hotter headline impulse and firmer-than-expected core inflation. Until the data show that pressure is fading, the Federal Reserve may have less flexibility to accelerate cuts, and markets may remain sensitive to every inflation signal.
For now, the evidence points to a more demanding policy environment. Stocks are under pressure, Treasury yields are higher and the US dollar is stronger. The next phase of the trade will depend on whether September’s energy shock remains concentrated in fuel or begins to reinforce broader inflation expectations.
Bull/Bear Verdict
Bull Case: If the 9.1% gasoline increase and 15.3% fuel oil increase prove concentrated in energy, the broader inflation pressure may moderate, allowing expectations for future Federal Reserve rate cuts to stabilize.
Bear Case: The firmer-than-expected core CPI reading, combined with gasoline rising 9.1% after a 3.9% August increase, could delay or slow anticipated rate cuts, keeping Treasury yields elevated and maintaining pressure on stocks.