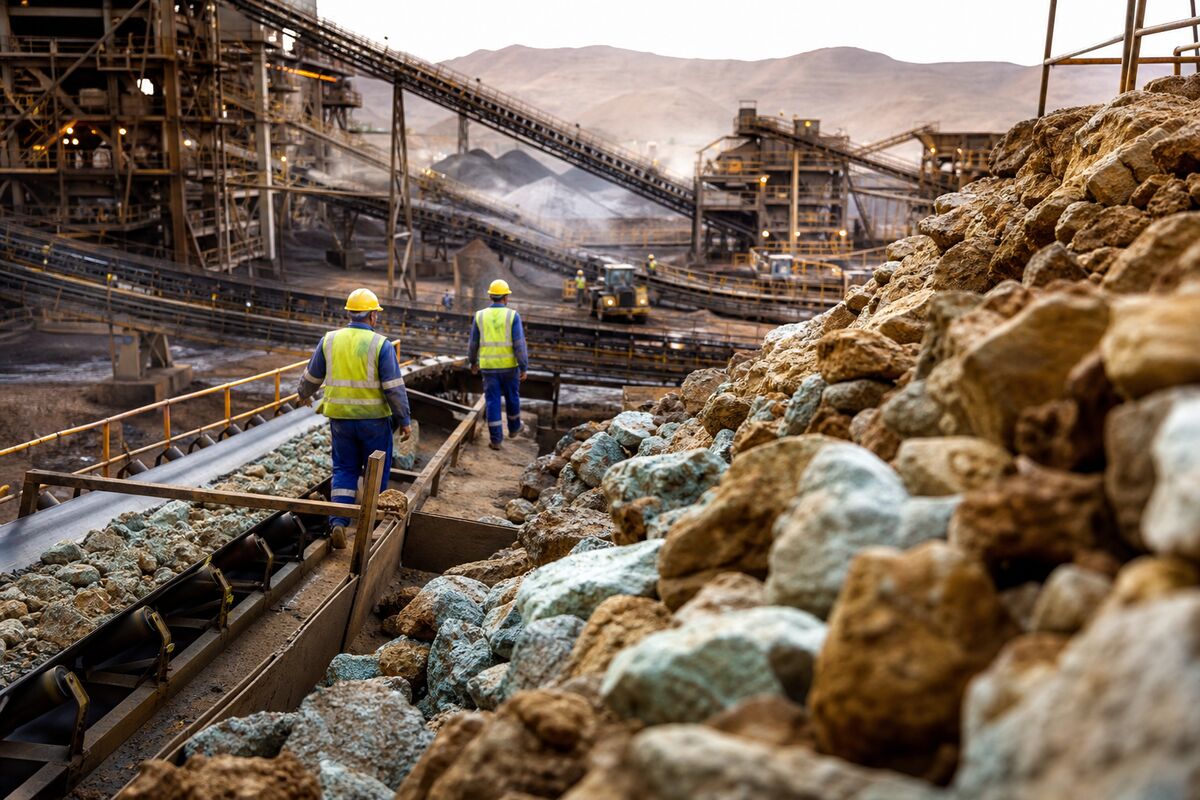
Electric vehicles may be assembled on North American factory floors, but some of the strategic ingredients behind them come from a far more complicated map. General Motors, or $GM, is now in arbitration with VAC after ending a supply agreement tied to rare-earth magnets used in EV motors.
The dispute is not merely a contractual footnote. It is a reminder that an automaker’s production plans can depend on materials whose supply chains carry procurement, geopolitical and execution risks well beyond the vehicle plant itself.
According to the reported details of the GM-VAC dispute, the arbitration follows GM’s termination of a rare-earth magnet supply agreement. The assignment does not provide financial damages, settlement terms or an outcome, so the central question remains unresolved: how the disagreement will ultimately be settled.
Why the magnets matter
Rare-earth magnets are used in electric-vehicle motors, making them a strategically important component of EV production. Their role gives the supplier relationship unusual weight. If the material is difficult to replace, a disruption may affect more than a single purchase order; it could complicate sourcing, production planning and the timing of vehicle programs.
That does not mean the arbitration itself will interrupt GM production. No such outcome is provided. But the dispute illustrates the kind of uncertainty that can emerge when an automaker changes course in a supply agreement involving a critical input.
Contracts are part of the supply chain
Automotive procurement is often discussed in terms of factories, mines and shipping routes. Contracts belong in the same conversation. A terminated agreement can leave questions around replacement supply, qualification of alternative vendors and the reliability of future deliveries. Even before any physical shortage appears, those questions may make production planning more difficult.
For an automaker, procurement certainty is valuable because EV programs require coordination across motors, batteries, electronics and final assembly. A supplier dispute involving magnets may therefore create pressure to revisit purchasing plans and contingency arrangements. The potential effect on costs is also straightforward: when a critical component becomes harder to source or requires a different supplier, the economics of the program could change.
Again, the available information does not establish that GM has suffered a production disruption or additional cost. It does show how a terminated supply deal can expose those vulnerabilities, particularly when the component is closely tied to the vehicle’s powertrain.
The geopolitical layer
The broader concern is China-dependent critical-mineral exposure. Rare-earth supply chains connect North American EV manufacturers to a geopolitical environment in which access to materials, processing and magnets may not be fully controlled by the final vehicle producer. That dependence can turn a commercial disagreement into a strategic issue, even when the immediate matter is an arbitration between GM and VAC.
For investors, the episode offers a useful lens on EV manufacturing risk. The market narrative often emphasizes demand, factory capacity and battery costs. Yet the GM-VAC dispute suggests that contractual resilience and critical-material sourcing deserve similar attention. A company may have a vehicle strategy, but executing it also requires dependable access to the specialized inputs embedded in that strategy.
The arbitration’s outcome is not supplied, and it would be premature to assign one. The more durable takeaway is that rare-earth magnets sit at the intersection of technology, procurement and geopolitics. For North American automakers, that intersection may remain a source of planning uncertainty as EV production expands.
Bull/Bear Verdict
Bull Case: The dispute could encourage GM to strengthen procurement planning and reduce exposure to a single rare-earth magnet arrangement, potentially improving supply resilience over time.
Bear Case: The terminated VAC agreement highlights uncertainty around procurement, production planning and costs for $GM, while China-dependent critical-mineral exposure could keep geopolitical risk elevated.