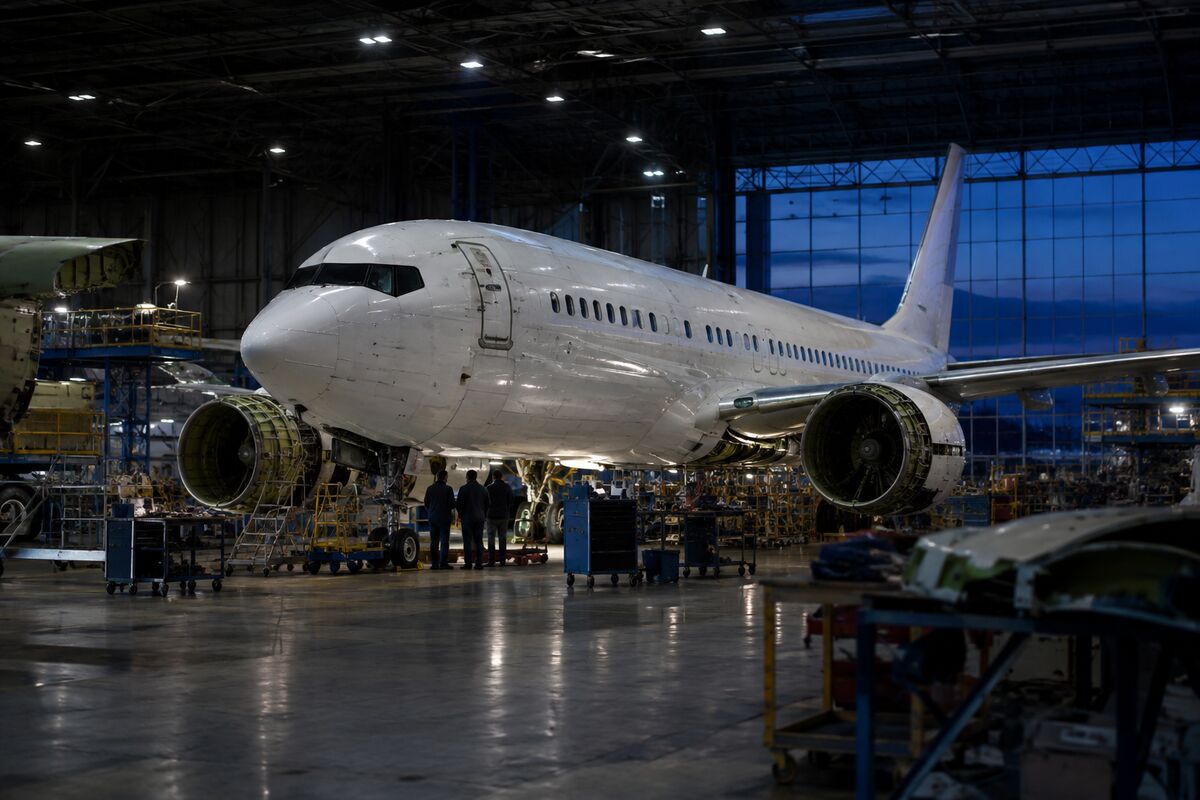
GE Aerospace has raised its 2026 earnings outlook, putting its services business at the center of the aerospace investment debate. The message is straightforward: demand for jet-engine maintenance and related support remains a powerful earnings driver, even without a specific share-price move or forecast figure disclosed in the report.
That matters because services revenue can give aerospace manufacturers a recurring stream of business after an engine enters operation. As aircraft accumulate flight hours, operators require inspections, repairs, replacement parts, and other maintenance support. GE Aerospace’s stronger services performance therefore may offer a more durable growth signal than equipment deliveries alone. Reuters reported the raised 2026 forecast and services-led growth on October 20, 2026.
Why services can matter more than deliveries
New-engine deliveries tend to be tied to production schedules, aircraft orders, and customer financing. Those factors can fluctuate across the industrial cycle. Maintenance activity, by contrast, is linked to the installed engine base and aircraft utilization. Once aircraft are flying, operators must keep engines inspected and operational, creating a recurring demand channel.
That structure may support aerospace earnings in several ways:
- Recurring demand: Maintenance requirements can continue across an engine’s operating life rather than ending with the original sale.
- Customer retention: Service relationships may connect manufacturers with airlines and other operators for parts, repairs, and technical support.
- Potential margin support: Specialized maintenance and proprietary parts can carry different economics from initial equipment deliveries, although the source material provides no margin figures.
- Visibility: A large installed base may give management a clearer view of future service activity than new-equipment orders alone.
Potential read-through for aerospace suppliers
GE Aerospace’s update could influence sentiment across US-listed aerospace suppliers and industrial stocks ahead of the broader third-quarter earnings season. The key question for investors is whether the company’s services strength reflects a company-specific improvement or a wider pattern of resilient maintenance demand.
If other aerospace companies report firm aftermarket activity, the sector’s growth narrative could gain support. Suppliers connected to engine components, replacement parts, repair work, and technical services may receive particular attention. The read-through remains indirect, however: GE Aerospace is the only company named in the report, and no ticker symbol, price data, forecast magnitude, or valuation measure was provided.
What to watch next
The next earnings updates may show whether service demand is broadening, whether operators are maintaining aircraft at consistent rates, and whether suppliers are seeing comparable strength in recurring support revenue. Investors may also focus on commentary about production, supply chains, and the balance between original equipment and aftermarket activity.
For now, the clearest data point is qualitative but important: GE Aerospace raised its 2026 earnings forecast and cited services as the key growth driver. That combination suggests a business benefiting from the long operating lives of commercial and defense aircraft, while leaving the size of the forecast increase—and its valuation impact—unquantified.
Bull/Bear Verdict
Bull Case: The raised 2026 earnings outlook and cited strength in services may indicate that recurring jet-engine maintenance demand is providing GE Aerospace with a durable growth engine and could support broader aerospace-sector sentiment.
Bear Case: The report supplies no numerical size for the forecast increase, price data, or valuation measure, so the market impact remains uncertain and the services strength may not automatically extend across other aerospace suppliers.